MISH'S
Global Economic
Trend Analysis

Recent Posts

Tuesday, June 26, 2007 8:51 AM


Misconceptions about Gold


Mish Moved to MishTalk.Com Click to Visit.

written by Trotsky, edited by Mish. see addendum.

Few markets are as widely misunderstood and subject to so many misconceptions as gold. Many of those misconceptions stem from gold's dual role as a commodity and money. This post will attempt to clear up some of those misconception with a few facts. Let's start with one key fact.

Gold is Money

How can I actually claim that 'gold is money'? After all, it is not used as official money anywhere and barring isolated instances of payments made from a digital gold account, it is unlikely that one will ever make a payment in gold these days.

In addition, central banks seem intent on 'demonetizing' gold, as the biggest CB holders of gold (except the US) continue to unload it, ostensibly to earn the higher returns provided by bonds. Selling gold for returns is actually a spurious argument, because reserves are just that: reserves. And the primary purpose of reserves is not to produce a return.

In spite of all this, we still know that gold is money, because it trades in the market as if it were money. Let's see if we can prove that thesis.

Gold Supply and Demand

If gold's price were determined by fabrication demand alone (jewelry and industrial uses), it could not possibly trade at a price of $650 oz.

Many gold analysts, from the mainstream to fringe groups such as the Gold Anti-Trust Action Committee (GATA) claim that they can predict what the gold price will do by adding up annual fabrication and investment demand (as well as dehedging demand by miners) and contrasting the resulting total with annual supply (mine supply, central bank selling, disinvestment and scrap). In short, they analyze the gold market in the same manner as they would analyze the copper market.

It should be immediately obvious that this can't be correct. After all, nearly the entire gold ever mined (approximately 150,000-160,000 tons) is still here. In short, the total potential supply of gold is some 97-98% greater than the gold produced every year (approximately 2,600 tons).

On that basis it makes no sense to apply traditional commodity supply/demand analysis based on annualized trends in the gold market.

Simply put, there is a big difference between commodities that are effectively used up (aside from scrap residual returning to the market every year) and a commodity the indestructibility and durability of which inter alia made gold the 'money commodity' in the first place.

Jewelry Demand vs. Monetary Demand

One can further illustrate gold's unique nature as money with a study of gold prices vs. jewelry demand. If record fabrication demand for gold (jewelry) must be good for the price of gold, then a historic high in jewelry demand should in theory coincide with a high gold price.

However, record high jewelry demand in 1999 - 2000 in actual fact coincided with a 20 year bear market low in the gold price - the exact opposite of what traditional commodity supply/demand analysis would suggest.

We can therefore conclude that there must be a source of gold demand that is of far greater importance than the jewelry and industrial demand components, and that demand constitutes the true driver of the price of gold in terms of fiat money.

Indeed, there is. This demand component is called 'monetary demand'. Monetary demand and the supply of gold is actually best described as the 'degree of reluctance of the current owners of gold to part with their gold at current prices' since, as mentioned above, some 160,000 tons are owned by somebody already.

De facto gold acts in the markets as if it were another currency rather than a commodity. It often keys off other currency cross rates, such as dollar/euro , and has a strong tendency to ignore all the typical supply/demand analysis thrown at it by the mainstream (including the World Gold Council which should know better).

A rising gold price usually begets falling jewelry demand, which is exactly what the theory of price elasticity would suggest. But at the same time, rising prices actually tend to stoke investment demand, just as a developing uptrend in the stock market tends to invite more demand rather than less as this chart, courtesy of Sharelynx Gold shows.

Click on the chart for a better presentation.


The above chart shows that the record high in jewelry demand coincided with the 20-year bear market low in the gold price. So what was driving the price of gold higher? We know it was monetary demand driving the price because the total fabrication demand for gold has been basically flat since 1999.

Ironically enough, the chart also shows the price of gold was falling for over 20 years even as fabrication demand was rising. This is further proof that fabrication demand is not the most important driver of the price of gold. Finally, it should also be noted that some jewelry demand, especially in India, is in reality monetary demand in disguise.

The sin of attaching importance to jewellery demand in gold price forecasts is engaged in by all the major brokerage houses. This leads even the best of money managers to making mistakes, as evidenced below:

Legendary value investor Jean-Marie Eveillard recently stated the following in a Fortune interview:

"When we started our gold fund in 1993 - which proved to be six or seven years too soon - I mistakenly thought that my downside was protected by the fact that jewelry demand was fairly vibrant. But I was wrong. I think gold moves up and down based on investment demand mostly."

The WGC (World Gold Council) meanwhile tries to gauge 'implied investment demand' respectively 'dehoarding' retroactively, by adding up known new annual supply (from mining, scrap, central bank selling and hedging) and contrasting it with known annual fabrication demand. The difference, it reckons, must represent 'implied investment demand' (presumably the demand from gold ETF’s figures in these calculations as well these days).

However, as we noted, investment demand is also expressing itself by the reluctance of current gold holders to sell at a given price. This reluctance can not be measured, and actual investment demand is therefore also not measurable.

Gold Mine Production vs. Total Demand


The above chart depicts another peculiarity of the gold market’s supply/demand situation: As the price of gold rises, mine production actually flattens out and falls. There are two reasons for this unusual response to higher prices.

  1. During low gold price environments, mines are forced to ‘high grade’ (i.e., mine higher grade portions of their orebodies). Once the price rises, they shift their mining activities to lower grade portions of their orebodies, that haven’t been economic to mine previously.
  2. During periods of low gold prices, exploration spending falls, so that once prices rise, very few new mines are set to open and take up the slack from depleted mines. It can take up to 7 - 10 years from the discovery of an economic orebody to the point when mining can begin.
What motivates monetary demand for gold?

To answer this question one must look back at how gold evolved to become money in the first place. First of all, it always was a commodity with a demand based on its usefulness for creating ornamentation and jewelry, so there was a prior demand for gold that made it useful in barter.

In addition to that, its non-corrosiveness, divisibility, fungibility and easy portability weighed in its favor for use as money. Lastly, its scarcity and the fact that its supply is unlikely to suffer sudden increases, regardless of the wishes of the money issuing authorities, made it a prime candidate to act as a store of value.

There is a single historical exception to this gold supply dogma, and that's when Spain imported (stole) gold from the New World in the 17th century leading to inflation in Europe. Nowadays, mine supply is around 2% of the total stock of gold per annum and it's highly unlikely there will be much deviation from this percentage. Thus a similar gold-based inflation today would be extremely unlikely.

This latter point - that the State can't create gold out of thin air - is what lies at the heart of the monetary demand for gold.

In our modern day fiat money system with its fractional reserves banking systems and free-floating paper currencies, gold is the only form of money safe from the depredations of central bankers. It therefore serves in the widest sense as a barometer of confidence in this central bank administered system.

Considering that the US dollar has lost about 97% of its value against gold since the Federal Reserve has been in business, one can conclude that confidence in fiat money has been waning rather precipitously over time. This trend is certain to remain a one-way street over the long term, with occasional fluctuations as confidence in paper (or digital) money waxes and wanes.

Unfortunately, this sad state of affairs doesn't seem to worry the engineers of inflation. They only get worried when it happens too quickly (so fast that everybody takes notice). One should add here that in the back of the mind of the typical monetary bureaucrat there is this little voice that says: "If push comes to shove, we can always take it back by force." After all, it wouldn't be the first time.

Time Preferences

In the shorter term, the motives of gold holders who to refuse to sell (possibly even adding to their position) often depend on immediate concerns such as real interest rates, inflation expectations, the spread between short and long term interest rates as a proxy for the likely bias of monetary policy, and the exchange value of the US dollar.

Typically gold is a counter-cyclical asset that does best in real terms when liquidity evaporates. At times however, there can be pro-cyclical demand when equity, commodity, and gold prices are all rising strongly, and liquidity is more than abundant.

In the end, such price fluctuations in gold are a bit like Warren Buffet's famous remark about the stock market being a 'voting machine in the short term and a weighing machine in the long term'. In the short term, all sorts of considerations can be used to 'explain' movements in the gold price, but in the long term, gold acts as the aforementioned barometer of confidence in central bank issued fiat money.

Up next: Why does fiat money seemingly "work" at all?

[The above link added after the fact for reference purposes.]

Addendum:

Mish asked me if I would consider writing a series of posts on his blog about gold. I was pleased to take advantage of his offer. Together we came up with the topics, I did the writing, and Mish did the editing. A question came up as to what name to make these posts under. The name “Trotsky” had its origins as a joke handle I started using a long ways back on Kitco. I'm as anti-Leon Trotsky as one can possibly be. I'm not particularly fond of the handle anymore, but it's now the name I am associated with and we decided not to change it on short notice.

Trotsky
http://globaleconomicanalysis.blogspot.com/

Monday, June 25, 2007 3:04 AM


Toggle Bonds - Yet Another High Wire Act


Mish Moved to MishTalk.Com Click to Visit.

While doing some research on "toggle bonds" and “covenant light” deals, I came across an article in the GlobeAndMail called Private Equity's High-Wire Act that describes both nicely. This following excerpt is further proof of just how insane credit lending has become.

Behind the veneer of the self-congratulation, jaw-dropping riches and plain excess – witness Blackstone Group chief Steve Schwarzman, who made $400-million last year and hired Rod Stewart to perform at his 60th birthday party – the first cracks are beginning to appear. Some private equity players say too many deals are getting done at prices that are too high; on average, buyouts firms in the U.S. are paying roughly 50 per cent more for assets than they were in 2001.

The bidding wars are great for shareholders of public companies, but afterward, they also leave those businesses encumbered with far too much debt, much of it borrowed under looser terms than ever. Some of the biggest buyout deals of the past few years – Freescale Semiconductor in the U.S., Masonite International in Canada – are already showing some financial strain.

Today, a few bankers have publicly voiced concern about foolish lending, among them Bank of America chief executive officer Ken Lewis, who recently got the attention of the world's banks when he said: “We are close to a time when we'll look back and say we did some stupid things.”

In the U.S., banks hold just 20 per cent of “leveraged loans,” a term that describes not just buyout loans but other junk debt, according the Standard & Poor's.

The other 80 per cent is held by institutional investors – hedge funds, mutual funds, pensions, insurance companies and so on. The biggest buyers are financial engineers who acquire a bunch of loans, pool them together as collateralized loan obligations, or CLOs, and sell them off in pieces – very often to those same hedge, mutual and pension funds.

CLOs didn't exist during the big buyout wave of the late 1980s, and they didn't become “dominant” buyers of high-risk loans until 2002 and 2003, says Steven Miller, who analyzes the speculative loan market for S&P. While they've been a haven for the banks as a place to easily offload speculative loans, the presence of CLOs creates a longer daisy chain – middlemen upon middlemen – dividing those loans up into ever-smaller slices.

The result is that the banks, now acting more as loan brokers, are less vigilant about the kinds of loans they arrange, since they know that they likely won't be holding the loan for long.

Does this sound familiar? It should – because it's similar to the way the U.S. subprime mortgage operated during its high-growth years. Mortgage brokers, scurrying to sign up clients as quickly as they could, were lax in weeding out customers with poor credit. When those borrowers began to default in large numbers, the usual buyers for subprime debt quit purchasing it, and those left holding billions in poor-quality loans – companies like New Century Financial – went broke, out of business, or swallowed their losses.

The fees for arranging loans are as alluring for the commercial banks as they were for subprime lenders.

“It's like crack cocaine for them,” says the unnamed private equity partner. In LBO deals, “the banks don't care any more about the [quality of] credit. As long as they can sell it all, they're fine.”

Large private equity firms know this and are taking advantage. The heated competition for their business means not only cheap money, but easy terms.

So-called “covenant light” deals, such as Kohlberg Kravis Roberts & Co.'s $26-billion takeover of First Data, remove many of the usual conditions attached to loans; borrowers aren't required to keep their debt below 6 times their annual EBITDA, for example, or to ensure that their interest payments consume no more than half of their cash flow. (EBITDA is earnings before interest, taxes, depreciation and amortization.)

The idea is to “make it harder for the banks to find a default that would allow them to call the loan,” says Jay Swartz, a lawyer at Davies Ward Phillips & Vineberg LLP who works on private equity transactions. How many big LBOs are being done covenant light? When it comes to deals by KKR, Blackstone Group and other large private equity shops, “virtually all” are done this way now, confesses a New York-based banker for a large Canadian financial institution.

Three years ago, U.S. firms taken over in LBOs had free cash flow that equalled 2.6 times their interest expense - so if the business took a dive and cash flow fell by half, they could still make their payments. That's no longer the case. The cash-flow coverage ratio has shrunk to 1.7 times, according the S&P's Mr. Miller, the lowest level since the bull market of the late 1990s.

These are the subprime borrowers of the corporate world, and they, too, have their own inventions for making a heavy debt load a little bit easier. The housing industry had adjustable-rate mortgages; Wall Street has "toggle bonds," which allow the borrower to choose to pay interest by issuing more bonds, paying even higher interest, instead of cash.

Toggle bonds are not a totally new concept, but they tend to be issued only in exuberant times. They have proven to be dangerous in an economic downturn.

It's easy to understand why a company would want to sell a toggle bond, but harder to reckon the appeal for those buying them. Who wants to lend money to a company that's so strapped for dough, it can't even pay its interest in cash?

The reasons are simple. Many hedge funds use borrowed money themselves to amplify returns. So all they need to do is find some debt that's yielding, say, 10 per cent, buy a lot of it with money they've borrowed at 7 or 8 per cent, and collect a healthy spread - and fat fees - in between.

And if that strategy explodes in their faces because they end up holding some worthless junk debt? So be it. For as long as it lasts, it's an easy route to profits. Hedge funds get into trouble and are forced to close shop all the time, but no one ever asks them to return their fees (generally 2 per cent plus 20 per cent of the investing profits).

"Why would you not just take the highest possible risk with other people's money? If there's literally no downside, it's the rational thing for you to do," says Mr. Fridson.

The history of such lowly debt like that is not very encouraging; usually, more than one-third of it goes into default within the first three years. It's not a question of whether a large LBO implodes, but when it will happen and who will be left holding the bag.
It's no secret there have been relatively few defaults on even the junkiest of junk so far this year. The reason is simple: companies that would (and should) have been wiped off the face of the earth by default were given a lease on life by investors willing to refinance that debt on insanely favorable terms to the debtors, regardless of risk.

“The process feeds on itself until the patient dies”

The speculative action in LBOs, junk financed buybacks, and toggle bonds is indeed quite like that of junkies hooked on crack cocaine. It's fitting that the words junk and dealers both apply. The only difference is this high comes from debt leverage instead of cocaine. And why not pile on the risk and shoot for the stars with as much leverage as possible? After all it's OPM (other people's money) being bet. In both cases the next fix takes more and more leverage to generate the same high. And in both cases the process feeds on itself until the patient dies. But before this all blows up, enormous fees are generated for the dealers, in this case investment bankers and hedge funds.

Fantasy Land for Corporate Treasurers

The Standard discusses toggle bonds in Junk bonds spark jitters.
"Defaults are almost non-existent today and, well, we know that doesn't hold forever," said Thomas Lee, who stepped down last year from Thomas H Lee Partners, the Boston-based takeover firm he founded 32 years ago.

"When the economy goes bad, defaults will spike up from 1 percent into the 9 percent level," Lee said at the Milken Institute Global Conference in Los Angeles last month. "If that happens then the financing part grinds to a halt" for LBOs, he said. More than half of the junk bonds sold this year were used to pay for leveraged buyouts and mergers and acquisitions, notes Barclays Capital.

Money is so easy to come by that for the first time some investors agreed to let borrowers choose to make interest payments in cash or in additional bonds. "This is fantasy land for corporate treasurers," said Edward Altman, a professor of finance at New York University's Stern School of Business.

The growth of toggle bonds is a symptom of too-easy credit, Fridson said. Giving companies the ability to pay interest with more debt rather than cash shows they "have a reasonable likelihood of needing to exercise that option," he said.

Companies are piling on debt even as the economy slows. Total debt for about 300 companies rated BB and B rose by 16 percent last year, double its growth in 2005, according to Fitch.

Ford Motor lost US$282 million in the first quarter and is US$23 billion deeper in debt than it was a year ago. The Dearborn, Michigan-based company's US$3.7 billion of 7.45 percent bonds due in 2031 trade at a yield premium of 4.63 percentage points, down from 5.38 a year ago, according to Trace, the bond-price reporting system of the NASD. Ford is rated Caa1 by Moody's.

More than US$108 billion of so- called covenant-lite loans, or those that do not hold borrowers to limits on quarterly debt, have been completed this year, compared with a total of US$36 billion in the previous 10 years, according to S&P's LCD.

"The normal thing is two to four years after the issuance for defaults," said NYU's Altman. "Deals with little covenants, toggles, push back the timeline. But it's gotta happen."
Note that as Ford went $23 billion deeper in debt the presumed risk of default dropped given that spreads fell by 75 basis points.

Postponing the Day of Reckoning

Investment News describes toggle bonds and distressed debt in general the situation in Returns on distressed debt piquing investor interest.
Distressed debt can be risky, but that hasn’t stopped investors from turning to it in search of extra yield, industry observers say. Returns on distressed debt — junk bonds with a very high likelihood of default — were a strong 11.4% in the first quarter, outstripping all other asset classes, according to a recent report from Standard & Poor’s in New York.

But there isn’t a lot of distressed debt available for those investors who hope to jump on the bandwagon, said David Keisman, an analyst at Moody’s Investors Service in New York.

There is so much liquidity in the market right now that financing is easy to come by, he said. Companies that normally would have found themselves in default have been able to refinance their debt, Mr. Keisman added.

But are these “rescues” permanent or are defaults merely being pushed off for a later date? That is a distinction Mr. Keisman said is impossible to determine until it is too late. “No one is forecasting much of a default rate in 2007,” he said.

There have been 10 sales of toggle bonds this year, totaling $5.14 billion — a record, according to S&P.

The effect of toggle bonds, as well as some of the rescue financing, however, will be to push off junk bond defaults to a later date, said Martin Fridson, chief executive of FridsonVision LLC, a New York high-yield research firm.

Junk bonds — and distressed debt, in particular — will continue to win fans, because it is hard to predict what the catalyst might be for a rise in defaults, said Rick Fulmer, a Denver-based vice president and bond trader with D.A. Davidson & Co. of Great Falls, Mont.

Because spreads between high-yield bonds and U.S. Treasuries are much tighter than normal, investors have to take on more risk for less reward. But the economy still is strong, and companies still are able to pay off their debt, Mr. Fulmer said.
The Catalyst

Here's an interesting sentence from the above article: "It is hard to predict what the catalyst might be for a rise in defaults."

I strongly disagree. The catalyst is easy to predict (even if the timing itself is difficult). It will be a sudden change in risk tolerances of hedge funds, investors, and/or others to do these deals.

I talked about sudden changes in sentiment in Consumer Sentiment Wanes as Housing Slumps.
Flashback Summer 2005

Floridians were camping out overnight in lines to buy Florida condos. Prices were soaring. Did prices start falling or did the pool of fools willing to buy Florida condos at increasingly absurd prices dry up first?

Flash Forward Summer 2007

Will stock prices drop first or will the pool of fools willing to finance increasingly absurd leveraged buyout deals and debt financed stock buybacks dry up first?
In 2005 the conventional wisdom was that it would take much higher interest rates to sink housing. Conventional wisdom was wrong: the catalyst was a sudden and sustained change in the willingness of fools to invest in Florida houses . In short: the pool of greater fools simply dried up.

Whether it's housing, leveraged buyouts, toggle bonds, distressed debt in general, or stock prices, it will be a change in appetite for risk that leads the charge.

With that thought in mind let's turn or focus on the question: "But are these 'rescues' permanent or are defaults merely being pushed off for a later date? That is a distinction [that] is impossible to determine until it is too late."

Too Late Already

I suggest that it is possible to determine whether or not it's too late. Furthermore I suggest that it's already too late.

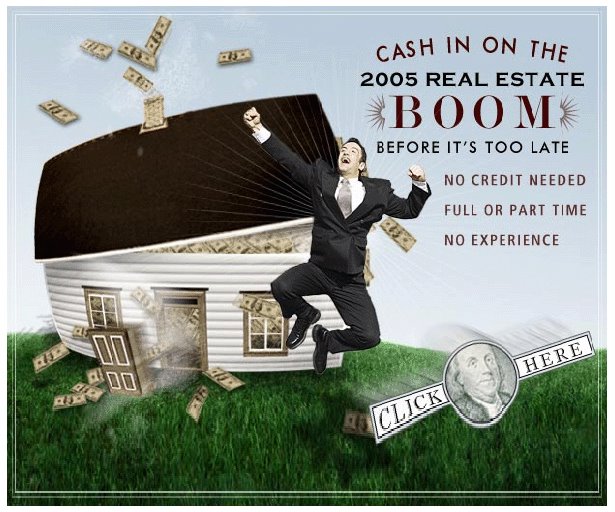
Flashback December 13 2005: It's Too Late. This is what I wrote:
I think it's too late.
In fact I know it's too late.
How do I know?
The following Email I received tonight should explain it nicely.
When you see stuff like this, not only is it too late, it's way too late.


Just and there was too much housing and subprime garbage in 2005 to be unwound, there is now too many toxic CDOs, toxic CLOs, toxic toggle bonds, toxic LBOs, and simply too much toxic stuff in general to be unwound. And when the unwinding attempt really gets going (it has now barely started) there simply will not be any bids for most of this toxic garbage. Want proof? Just ask Bear Stearns. The debacle at Bear Stearns is but a drop in the bucket for what's to come.

Mike Shedlock / Mish
http://globaleconomicanalysis.blogspot.com/
Sunday, June 24, 2007 1:38 PM


Mike Morgan June Update


Mish Moved to MishTalk.Com Click to Visit.

Following is a June update from Mike Morgan at MorganFlorida. I will dispense with blockquotes in the interest of saving space. Note: I receive weekly updates but only have permission to post one a month. Here goes from Mike Morgan, with a specific focus on WCI....

June Update
Mike Morgan

Quote of the Week
– “I don’t believe time is on their (WCI) side, given the deterioration of the Florida condo market.” Dan Oppenheim, Banc of America

What Was He Thinking Quote - "We do think if you're dumb enough to buy a home builder, you ought to buy us," Ryland Group Inc. Chairman and Chief Executive Officer R. Chad Dreier, at the JP Morgan Conference this week.

Market Conditions – We’re seeing a pickup in traffic, but the buyers have become quite aggressive in low bidding. One of my clients offered $300,000 on a $350,000 home and would not raise the bid. The seller was not interested in even considering the bid, and did not want to counter. With rising inventory, the only way for public builders to compete with traditional sellers, foreclosures and short sales, is to drop prices. I believe we have reached a point where builders’ margins have been reduced to low single digit and negative margins.

WCI – The big news is certainly WCI. The Board decided to delay the annual meeting at Icahn’s request. This gives him time to unravel his positions. WCI noted that Icahn is conducting tours of the properties. Unfortunately, he’s touring the properties with WCI representatives instead of someone who would show him what the real story is.

Debt – Icahn must have realized, if he gained Board seats it would have triggered the debt at 101%. This alone was reason enough for Icahn to walk away. Even without triggering the debt, I believe WCI is facing a debt crisis. They either are or will shortly be in violation of covenants. Will the banks declare a default? No. The banks realize there is no equity, and the banks already have enough problem loans in the housing industry. Recent downgrades of several major builders to junk status is warning enough that WCI or anyone considering WCI has a debt crisis looming.

[Mish note: I asked Mike to clarify that debt triggering event. This was his response: The debt covenants have restrictions for control of the company. If somebody new gets on the board, the debt holders can call in the debt at 101% of face value immediately. You can find that in the offer Icahn made under some of the notes. So, as you can see, there was never any chance of Icahn getting on the board. If they were going to say yes to him, he would have figured out a way to wiggle out. Instead, Ackerman and Company made Icahn’s job a lot easier by keeping the stock high to give Icahn a chance to unravel his positions. This may have been nothing but a shell game from the start ... with Icahn NEVER having any intentions of buying WCI at $22.]

Lawsuits – We’re hearing of more lawsuits brought by buyers against WCI for delay in delivering units. I also anticipate a lawsuit from Ichan against WCI, Ackerman and Hoffman. Ackerman and Hoffman sold stock north of $21, even though they told shareholders Icahn’s offer was not enough at $22. When Icahn completes his due diligence, I would find it unlikely that he doesn’t realize WCI has misrepresented the health of the company.

Votes – I believe Icahn had more than enough votes to get on the board. Here are the 10 largest institutional holders as of March 31, 2007:

Carl Ichan and Affiliates – 14.5%
Sandell Asset Management – 9.7%
SAC Capital Advisors 9.5%
Highbridge Capital Management – 8.5%
Dimensional Fund Advisors – 7.1%
Hotchkis & Wiley – 6.6%
Canyon Capital Advisors – 5.9%
Morgan Stanley – 4.9%
D.E. Shaw – 4.9%
Neuberger Berman – 4.8%

In addition to the institutional holders, Hotchkis controls another 7.6% of the stock through two of their funds.

The problem he faces is demonstrating what he is going to do with the debt and the company if he influenced enough of the large holders to back his efforts. With no hidden value coming to the surface, it’s clear Icahn has no choice but to back away swinging.

Time – Dan Oppenheim summed it up best with our Quote of the Week. As we move into the slowest selling season, and the Florida inventory of towers and single family homes continues to build, WCI’s value drops daily.

Listings at Bal Harbour – There was one new listing in Bal Harbour this week, but the startling fact here is the withdrawal of 29 listings. As of Saturday, there were 69 active listings in on the Miami-Dade MLS board. The drop in the number of listings can only be attributed to what I discussed last week. If your property is listed within a time period set by the lender, they know you are a flipper, and they will not finance the property.

It’s obvious now that sellers are finding this out the hard way. As we get closer to the WCI proposed closing date, buyers are finding it difficult to obtain financing. Absent financing, many of these buyers will not be able to close . . . even if they were dumb enough to think they can flip these properties.

I must update last week’s number, since I found a glitch in the Miami-Dade MLS system. It appears three agents have listed properties with a misspelling of Bal Harbour as Bal Harbor. This means there were 102 listings last week, one new listing this week, and 29 withdrawals. The current number of MLS listings in Bal Harbour are 69. However, there may be more listings entered improperly, and there are many pocket listings that agents will not put on the MLS in order to get around the financing restrictions.

Listings at Harbour House – This is the condo that shares the Bal Harbour property and entrance. There are 26 listings in the Harbour House.

Other Listings – In Area 22, where Bal Harbour is being built, there are condo 1,813 listings over $500,000. There are another 3,500 under $500,000!

Builder Downgrades – Lennar joins the ranks of builders facing downgrades by Moody’s and S&P. On Friday, Moody’s put Lennar on a watch list, which means they see at least a 40 percent chance of a downgrade to negative at some point in the next 18 months.

Bankruptcies – The Wall Street Journal reported on Georgia home builders this week, and the bankruptcy filing of Meyer-Sutton. It’s a small builder, but is it just a sign of what is to come. In Pennsylvania, Elliott Building Group filed for bankruptcy last week. And let’s not forget Kara Homes, the largest private builder in New Jersey. They filed for bankruptcy as well.
The Journal also noted that BOA foreclosed on five property developments in Georgia, and they did so at a loss to the 20% hit to the original principal amount. For the larger banks, these failures are not a problem But for the smaller local and regional banks, these issues spell disaster.

Here are some startling statistics about banks with Georgia loans: First Nation, Gainesville Bank & Trust, NetBank, Community Bank and Bankers Bank all had more than 50% of their total loans in construction, ranging from 54.2% to a whopping 78.8%.

Subprime Goes to Wall Street – Goldman Sachs noted that earnings were hit by subprime problems. Goldman Chief Financial Officer David Viniar said in a conference call that the subprime sector's woes are not over and to expect "more pain" before the problem is purged.
"The subprime saga will not be sufficient to derail the U.S. and world economy," Lehman's Jack Malvey said at the Reuters Investment Summit in New York." Well, you’ve got to wonder why he would even make this statement, unless some of his colleagues are discussing a crisis far greater than the talking heads will lead you to believe.

And here’s the proof: ABN Amro fears a world housing crisis is looming. A note from ABN Amro noted fears for the health of the US housing market have captured headlines, but the degree of over-valuation is more severe in Britain, Australia, Spain and Ireland. ABN Amro found that UK residential property is 50% overvalued, whereas US houses are 25% too expensive.

Last month UBS said it would shut down Dillon Read Capital Management after they lost $123 million . . . and subprime was cited as a chunk of this. And this week Bear Stearns seized control of $400 million of the assets of an internal hedge fund out of fear they were not going to meet a margin call. Bear Stearns puts the finger on the fund’s bets on risky home loans. We’ve got a more than a trillion dollars in questionable housing boom related loans out there, including residential, commercial and builder loans.

Subprime Goes to College – It’s not just housing. Here is a link to an article from The New York Times about subprime college loans, with grads burdened with $900 a month payments at rates as high as 20%.

Mortgage Rates – At the beginning of 2007 the rate on a 30 year fixed was 6.18. It now stands at 6.74. On a $300,000 home, that means an additional $1,680 a year in mortgage payments or $140 a month. Adjustable rate loans have accounted for 25-33% of loans since 2004.

Most of these loans are at rates under 4%. Now you have a hike in the monthly mortgage payment approaching $700. Between now and the end of the year, it is estimated more than $100 billion in subprime loans are scheduled to reset.

The rise in rates means a much lower affordability index for seller, including builders. A homeowner that qualified for a 4% interest only ARM a couple of years ago based on a $1,500 a month mortgage could afford a $450,000 home. If that buyer were able to find an interest only mortgage today, they could only afford a $267,000 home! That’s a 40.66% hit to the price of the home they can afford. I don’t know of any builders that had 40% margins . . . even at the peak.

It gets worse. It is tough to find 100% financing - interest only lenders now. So if this were a 90/10 loan that cuts a lot of other folks out of the market.

Mortgage Games – Despite what you hear from the mortgage companies and the feds, you still see an awful lot of commercials and internet ads for no-doc loans, 100% loans, etc. And then there is the cash back deal. This involves hiking the sales price of the home artificially. As long as you can get an appraiser to manipulate the numbers, you can pull this off. Basically, the price goes up on paper, but the seller agrees to give the buyer cash-back at the closing. Nothing new here, but it seems to be new for Wall Street and the media. Here is a link to an article from The New York Times called Payback Time discussing Cash Back.

And if you think Cash Back is creative, how about loans piggybacking on someone else’s credit. The New York Times is definitely on the case of mortgage fraud.

Spillover – When a family in a $300,000 homes is faced with a $700 a month mortgage hike, there will be spillover.

Condo Spillover – Here’s one you will not hear from many folks. When units in a condo are foreclosed there is no unit owner to pay the Condo Association Fees for maintenance, taxes, insurance, utilities, etc. The burden falls on the folks that did close and are still alive. If you have a building with a 50% foreclosure, that means the COA fees double for the remaining owners. This will have a domino effect on foreclosures, sales prices and overall sales.

Lawsuits – This is a booming area of the economy. Lawyers continue to file lawsuits against builders for a host of issues ranging from defective homes to predatory lending. But here’s a twist. Coast Bank (Florida) shareholders filed suit against borrowers. Fifty borrowers shot back with their own lawsuit claiming the bank schemed to defraud them. The attorney for the borrowers says he is going to file another 75 lawsuits for borrowers who claim they are stuck with homes and lots worth less than what they owe.

Coast Bank made $110 million in loans to 500 customers of Construction Compliance Inc., a now bankrupt home builder on the Gulf Coast. The attorney for the borrowers said he may wind up working out the loans with the FDIC if they take over the bank. And he may succeed, since regulators recently hit Coast Bank with a cease and desist order for unsafe and unsound banking practices.

Countrywide Financials REO’s – A picture is worth a 1,000 words. Or in this case, 8,726. This is a visual of Countrywide Financials REO’s


Duetsche Bank – DB initiated 325 foreclosures against condo owners in Miami-Dade, Broward and Palm Beach during the first four months of this year for a total unpaid mortgage value of $70 million. DB claims they have either sold these loans, securitized them or they are acting only as a trustee. Okay, I’ll buy that. But what I won’t buy, is the condo crisis is not going to touch anyone. Somebody, somewhere is going to get clobbered. U.S. Bank and Bank of New York are two other banks that have initiated large numbers of foreclosures, 211 and 164 respectively. Not far behind is Wells Fargo with 131 and HSBC with 104. I guess they sold all their loans as well.

Unfortunately for these big banks, I think we are going to see some lawsuits from the people and pools that bought these loans . . . and there are still more than 100,000 condo units that have not been delivered.

DB was overall the top dog in foreclosures with 2,125 condo and single family foreclosures in the first four months of this year, representing $507 million. DB’s share of the South Florida mortgages in foreclosure represents 17% of the total.

Virginia Market Numbers – These are April numbers, as they lag in reporting like so many other boards. For the Metro DC market sales fell 12.17% in April from 1,857 in April 2006 to 1,631 in April 2007. So despite what you hear, this market is not “dancing on the bottom,” “ready to rocket,” or “holding up well.” And the average price fell 2.43% from year ago pricing to $543,166.

Orlando Market Numbers – For the Orlando MSA new listings rose 6.31% in May from April with 6,200 new listings. A year ago there were 2,842 new listings in May.

Sales - Sales in the Orlando MSA for May rose 1.30% to 1,550 from April, but May’s numbers represented a 45.46% drop from May 2006 sales of 2,842. What more can I say.

Florida Woes – This week our legislature passed a proposed tax relief bill. It will go on the ballot on January 29. It’s ugly. Local governments must roll back budgets by $15.6 billion. Florida schools lose more than $7 billion over the next five years. That should be great for a state that already lags the nation in education. Florida ranks 32 in teacher salaries.

Florida is going to be facing monumental budget problems over the next 3-5 years. On the bright side, this will probably attract more buyers, but for those that understand the dynamics, it will be an easy decision to look at NC, SC or GA versus Florida.

One more comment here that is going to hurt. Businesses do not have a property tax cap. We have already seen 400% jumps in property insurance for businesses over the past few years. If the current tax proposal passes, everyone agrees businesses will be the hardest hit . . . with no protection, no caps and a big budget deficit to fill.

NAR Economist in Florida – The NAR’s new Chief Economist, Lawrence Yun, spoke in Florida this week. He predicted a “sonic boom” for Florida if the Legislature succeeds in bringing insurance premiums back to earth. He didn’t paint as rosy a picture as David Lereah has done, but he is sorely mistaking if he thinks Florida can control the insurance premiums.

The State of Florida is now the largest insurer of homes in Florida. They lost a couple billion dollars two years ago. They are facing more red ink now . . . and that’s without any hurricanes in two years. A repeat of a Hurricane Andrew today, would bankrupt the State of Florida.

In addition to the property tax issues discussed above, taxpayers foot the bill for the homeowner insurance deficits. So that means if you are insured with Allstate, and your neighbor is insured with the State of Florida, you are paying part of your neighbors insurance bill!

Yun did follow in Lereah pattern as Chief Cheerleader, when he said there is nothing alarming about the housing markets in this region. “It is very, very manageable,” he added. That doesn’t balance very well with a report in the St. Petersburg Times, where they noted that, “an economist suggested the gap between incomes and home prices would depress housing values 40 percent.” Unfortunately, they didn’t name this brave soul.

Mortgage Bankers Association on Florida – According to Doug Duncan, MBA’s Chief Economist, “[t]he number of houses and condos on the market is so large that it would take almost three years to sell them all in Palm Beach and 31 months in Broward, if the pace of recent sales continue.” He categorized the foreclosure crisis in Florida as acute. But he didn’t limit it to Florida. He said the percentage of payments nationwide for subprime that were more than 30 days past due has jumped to 15.75%.

Video of the WeekFlorida Auctions. The builder is Levitt.


Disclosure: Of the stocks referenced today, I have no positions but I am involved in two lawsuits with Lennar. I am the defendant.

The Shadow

Thanks "Shadow"
Mike Shedlock / Mish
http://globaleconomicanalysis.blogspot.com/

Last 10 Posts


Copyright 2009 Mike Shedlock. All Rights Reserved.
View My Stats